Skip to content
MEET KEVIN WOOLLEY

Serving Utah Families & Business Owners Since 2009

Helping Families & Business Owners Make Insurance Decisions They'll Feel Good About for Years to Come

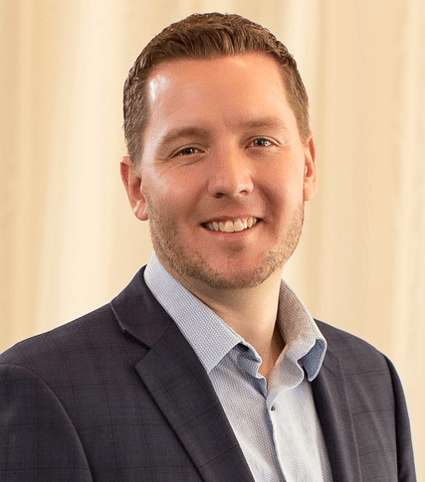
Professional headshot of Kevin Woolley, founder of Woolley & Woolley Insurance Group in Murray, Utah.

For more than 17 years, I've helped families and business owners navigate one of life's most important financial decisions: protecting the people, businesses, and dreams they've worked so hard to build.

Since becoming licensed in March 2009, I've helped more than 3,300 clients, written over 6,000 life insurance policies, and personally assisted families through 163+ life and disability insurance claims.

Some of my clients simply need affordable life insurance to protect a growing family or pay off a mortgage.

Other clients come to me after they've been declined for coverage, are buying a business, need to satisfy an SBA loan requirement, or simply aren't sure what to do with a life insurance policy they've owned for years.

No matter how straightforward or complicated the situation, my goal is simple: Help people make insurance decisions they'll still feel good about years from now.

Experience is Measured by the Promises You've Kept

17+

Years
Licensed

Helping families and business owners make confident insurance decisions since 2009.

3,300+

Clients
Helped

Families and business owners I've personally helped navigate their insurance decisions.  

6,000+

Policies
Written

 Life insurance policies written for needs ranging from simple family protection to complex business planning.

163+

Claims Personally Assisted

 Personally helping clients & families navigate life & disability insurance claims when their coverage was needed most.

Behind every one of those numbers is a family, a business, or a promise that mattered.

OUR ORIGIN STORY

Why Woolley & Woolley Exists

In the early 2000s, my dad began experiencing dizziness and symptoms similar to Parkinson's disease. After years of testing and countless appointments, specialists still couldn't give him a definitive diagnosis. Eventually, his condition forced him to medically retire. Around that same time, my mom asked me to help organize their finances, refinance their home, and see if I could help my dad qualify for life insurance. Creating their budget and refinancing their home was relatively straightforward.

Finding life insurance for my dad was anything but straightforward.

For the first time, I experienced what so many families eventually discover: life insurance is easiest to obtain when you're healthy. Once serious health problems develop, your options become much more limited. It didn't matter that they had worked hard their entire lives. The insurance companies only saw the medical file.

One day, while reviewing their budget with my mom, she looked at me and asked,

“Kevin... why don't you do this for other people?”

I laughed. It was 2008. The economy was collapsing, I had a secure job, and starting a new career during a recession sounded like one of the worst ideas imaginable. Then, just a few months later, that "secure" job disappeared. Instead of looking for another version of the same career, I decided to take my mom's question seriously.

 
I made myself a promise.

I wasn't going to stop learning until I figured out how to get my dad covered with life insurance. Eventually, I did just that. Today my dad still has his coverage. But what changed wasn't just his insurance. That experience changed the way I approach every client who sits across my desk.

I know what it's like to worry if someone you love is insurable. I know what it feels like to hear "no" and wonder if that's really the final answer. I've learned that sometimes the difference between a decline and finding a solution isn't luck or even a clean bill of health. It's having someone who's willing to slow down, understand the whole story, and find the right path forward. That experience taught me something I've carried with me ever since:

Before recommending a product, understand the person.
 

Every family has a story.


Every medical history is different.


Every business has unique challenges.

That's why I don't believe in treating every insurance case the same or blindly submitting applications and hoping everything works out. Whether someone needs a simple term policy, coverage for a growing business, or has been declined multiple times before, my job is the same: Understand the story first. Then find the solution.

Kevin Woolley’s father, whose experience obtaining life insurance inspired the founding of Woolley & Woolley Insurance Group.

My parents today.

The Reason Woolley & Woolley Insurance Group Exists.

REAL CLIENT STORIES

Every Story is Different

Every insurance case has a story. Some are straightforward. Others require persistence, creativity, and years of experience. Here are three that have shaped the way I practice today.

01

A Promise Kept During COVID

In late 2020, one of my clients came to me because his term life insurance was about to expire. The premium was about to jump from $94 per month to more than $2,100 per month. We looked at his options, he purchased a new policy with better rates, and we planned to let the old policy naturally lapse over the coming 60 days.

A few weeks later, I learned that he'd become seriously ill with COVID and was hospitalized. As the days passed and his condition worsened, I couldn't shake the feeling that I needed to have an uncomfortable conversation with his wife. When we spoke, she was hopeful he'd be coming home soon, but the tone in her voice told a different story. I told her I'd been having an impression I couldn't shake and asked if she'd be willing to hear me out. She agreed.

I suggested she seriously consider paying the past-due premiums on the old policy and keeping it in force just a little longer.

“If he comes home, we can let it lapse later. But if he doesn't, you'll be grateful it's still there.”

Two days later, we made the payment. Two days after that, her husband passed away.

THE OUTCOME

Because the old policy was still active, his family received the full $500,000 death benefit in addition to the new $125,000 policy we had recently put in place. Afterward, I worked directly with the insurance companies, his physician, and the mortuary to handle the claims process so the family could focus on grieving instead of paperwork.

I'll never forget the hug his wife gave me after everything was finished. She looked at me and said, “I'm so grateful for you.”

How this shaped me

That experience reinforced something I already believed: sometimes the hardest conversations are the most important ones and my responsibility as an insurance advisor doesn't end when the policy is delivered. Sometimes that's when it truly begins.

02

Protecting a Business, Not Just a Policy

Two young engineers came to me in early 2025 after purchasing a manufacturing company that builds carbon fiber tanks used around the world. Like many new business owners, they initially thought their biggest concern was satisfying the lender's life insurance requirement. As we talked, it became clear that was only one piece of a much larger puzzle.

Their purchase involved bank financing secured by their homes, seller financing, multiple selling owners, two new partners, attorneys, CPAs, and more than $5 million in financial obligations that would have to be addressed if one of the new owners died unexpectedly.

Rather than simply placing a policy to satisfy the lender, we stepped back and looked at the entire picture.

Working with their team, I designed a life insurance strategy to fund cross-purchase agreements between the new partners, an entity purchase agreement for the remaining selling owner, and a series of laddered term policies that would gradually decrease as the business debt was paid down. The insurance strategy was built to match the business's changing financial obligations over time instead of treating every dollar of debt the same. The case took nearly ten months to complete.

Along the way, I worked through underwriting challenges, financial justification, business valuations, and coordination with the company's attorneys and CPA to make sure the insurance fit within the larger plan.

THE OUTCOME

In the end, every policy was approved. The financing requirements were satisfied, and the owners could move forward knowing they had a plan in place to protect their families, their investment, and the future of the company.

How this shaped me

Business life insurance is rarely about buying the largest policy possible. It's about understanding how the business is structured, what needs to be protected, and how those needs will change over time. When I understand the whole picture first, I can often build a solution that's both more effective and more cost-efficient.

03

Finding Value Where Others Saw None

In 2023, I connected with one of my clients because the 10-year term life insurance policy he had purchased in 2013 was approaching the end of its level premium period. His premium was scheduled to jump to more than $700 per month. At age 75 and with significant health challenges, he believed his only realistic option was to cancel the coverage and walk away. Fortunately, we had one more conversation before he did.

THE OUTCOME

We reviewed all of his options, including allowing the policy to lapse, continuing the coverage at the higher premium, converting it to permanent insurance, and exploring whether the policy might qualify for a life settlement. After weighing the trade-offs, he decided to pursue the settlement. Ultimately, we were able to convert the coverage and complete a life settlement that paid him $11,377 for a policy he had every intention of simply walking away from.

When I accounted for the premiums he'd paid over the previous decade, his original life insurance had effectively cost him less than $9 per month. But the outcome wasn't just about the money. It was about helping him recognize that something he thought had become worthless still had value.

How this shaped me

One of the most common mistakes I see is assuming an older life insurance policy has no value simply because it's no longer needed or has become too expensive. Sometimes that's true—but sometimes there are options the policy owner doesn't know exist. Before walking away from a life insurance policy, understand what you own and what your options are.

Why I Still Love This Work

After more than 17 years, people sometimes ask what keeps me motivated. The answer is simple.

I still enjoy sitting across the table from someone who's overwhelmed, helping them make sense of a complicated situation, and watching them leave with confidence instead of uncertainty.

Some of the people I work with become clients. Many of the people I first meet as clients become friends over the years.  Every one of them is trusting me with something they've spent a lifetime building.

I don't take that responsibility lightly.

If you're facing an insurance decision—or just aren't sure what your best options are—I'd be happy to talk through it with you.